Landed Property Guide
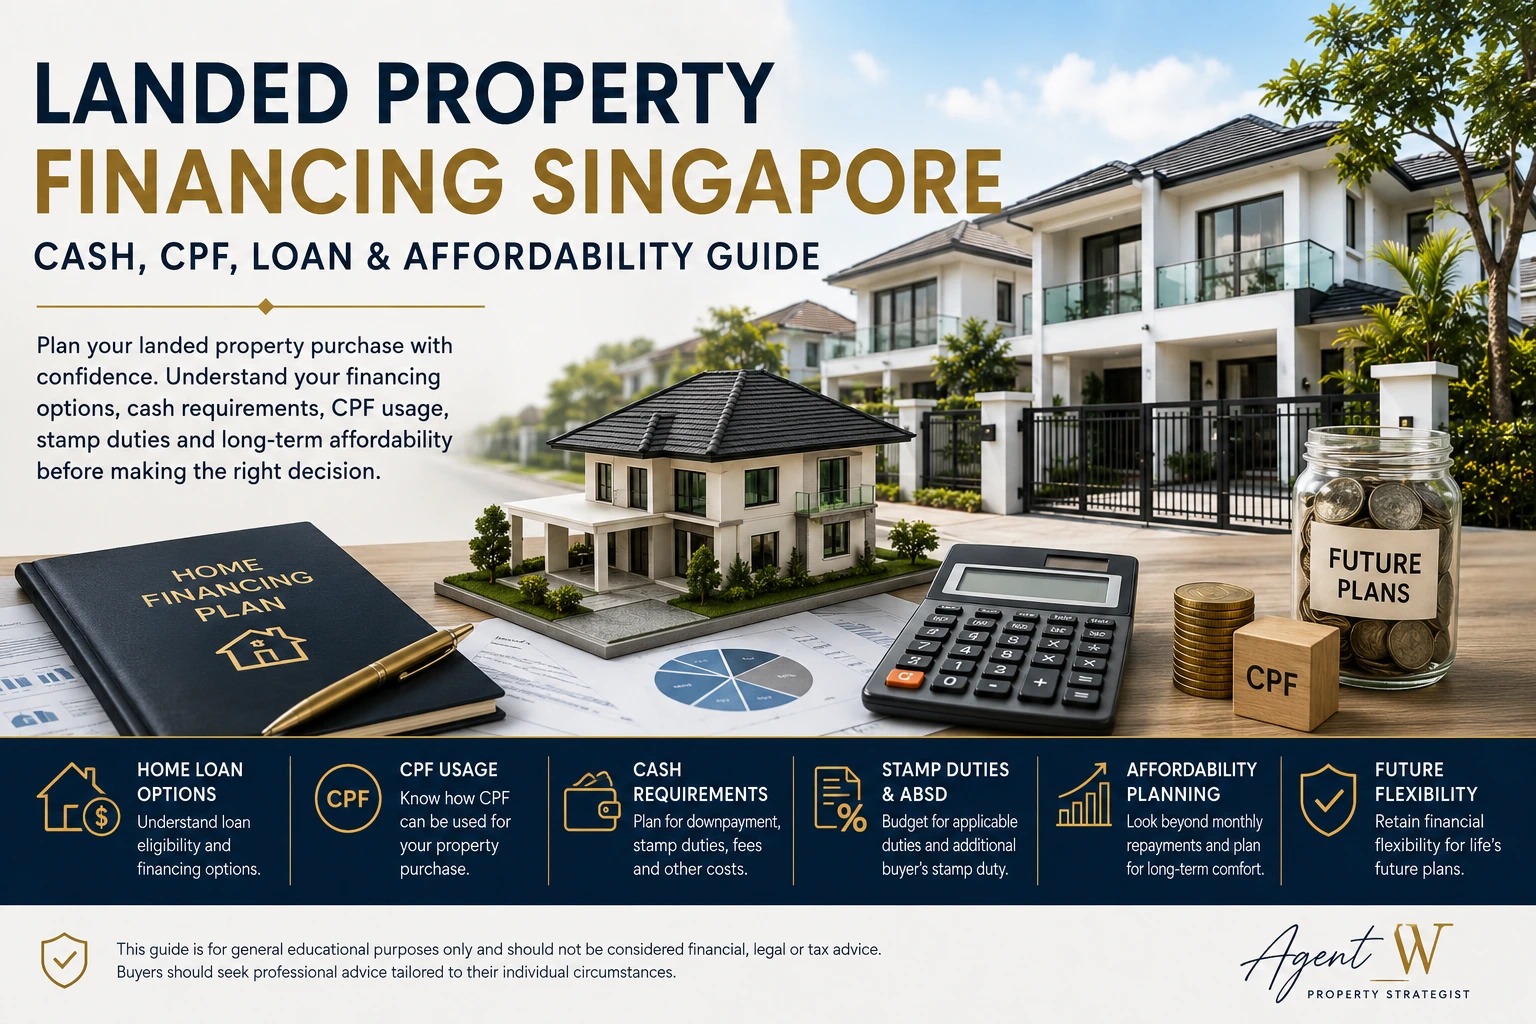
Landed Property Financing Singapore: Cash, CPF, Loan and Affordability Guide
Buying a landed home may involve a larger financial commitment than many other residential property purchases. Beyond the purchase price, buyers may need to consider financing, CPF usage, stamp duties, cash requirements, renovation costs and long-term affordability before making a commitment.
Financing a Landed Property Requires More Than Loan Approval
Many buyers begin by asking how much they may be able to borrow. While loan eligibility is important, financing a landed property usually requires a broader assessment than simply obtaining the highest possible loan amount.
Buyers may also need to evaluate their available cash, CPF savings, stamp duties, legal costs, renovation expectations and the financial flexibility they wish to retain after completion. Looking at these factors together often provides a more useful picture than focusing on monthly instalments alone.
This guide provides a general educational overview of the financing considerations buyers commonly review when planning a landed property purchase in Singapore. Actual financing, CPF usage and cash requirements depend on the buyer's circumstances, the property and prevailing rules.
Financial Planning
Why Landed Property Financing May Be Different
Higher Purchase Values
Landed homes may involve higher purchase values than many other residential property types, which can increase the amount of cash, CPF and financing required.
Larger Upfront Commitment
Buyers may need to plan for the downpayment, stamp duties, legal fees, valuation differences, renovation expenditure and contingency funds.
Long-Term Ownership Costs
Financing decisions may affect future cash flow, maintenance capacity, renovation planning and the buyer's ability to respond to changing circumstances.
Multiple Costs Work Together
Loan amount, CPF usage, cash contribution and transaction costs should be considered together rather than treated as separate calculations.
Major Financial Components Buyers Commonly Plan For
Home Loan
Financing may form a substantial part of the purchase. Buyers may compare loan options while considering repayment comfort, loan tenure, interest-rate changes and future financial commitments.
Cash Contribution
Cash may be required for portions of the purchase that cannot be financed or paid using CPF, as well as for other acquisition and ownership costs.
CPF Savings
CPF Ordinary Account savings may support eligible property payments, subject to prevailing rules, applicable limits and the buyer's individual circumstances.
Stamp Duties and Legal Fees
Buyers should also plan for applicable stamp duties, legal fees, valuation costs and other transaction expenses before committing to the purchase.
Renovation and Contingency Funds
Landed homes may require renovation, repair or upgrading expenditure. Buyers may wish to preserve a contingency buffer rather than allocating all available funds to the purchase itself.
A Useful Starting Point
A buyer's purchase budget should ideally account for both acquisition costs and the financial position remaining after completion.
Loan Eligibility Is Only One Part of Affordability
A lender may assess income, existing financial commitments, age, loan tenure, property valuation and other relevant factors before determining the amount it is prepared to lend.
The maximum loan available should not automatically be treated as the most suitable loan. Buyers may wish to consider how monthly repayments fit alongside family expenditure, insurance, renovation, maintenance and future financial objectives.
Indicative Loan Assessment
Buyers may find it useful to obtain an indicative financing assessment before making serious offers or committing to a purchase timeline.
Review income and existing debt obligations
Consider the likely loan tenure
Understand that actual approval remains subject to the lender
Allow for the possibility of a lower valuation
Repayment Comfort
A comfortable repayment level may differ from the maximum amount permitted under prevailing lending rules.
Consider future changes in household income
Retain room for maintenance and renovation costs
Avoid relying entirely on variable income
Keep emergency liquidity after completion
CPF Usage Should Be Planned Together With Cash Flow
CPF Ordinary Account savings may be used for eligible residential property payments, subject to prevailing rules and applicable limits. The amount a buyer is able or willing to use may differ from the total CPF balance available.
Buyers may wish to consider whether using a large portion of their CPF leaves sufficient flexibility for future instalments, other housing needs and broader retirement planning.
Potential Uses
Eligible portions of the purchase price
Applicable stamp duties where permitted
Eligible legal and transaction fees
Monthly housing instalments where applicable
Planning Questions
How much CPF should remain after completion?
Will CPF be needed for future instalments?
Are there applicable usage limits for the property?
How does CPF usage affect future sale proceeds?
CPF can support a property purchase, but it should not be viewed as a substitute for cash-flow planning. The amount used should be considered together with the buyer's financing, retirement and future property plans.
Cash Requirements Extend Beyond the Downpayment
Buyers should avoid calculating the required cash based only on the minimum cash portion of the downpayment. A landed-property purchase may involve several other cash commitments before and after completion.
Valuation Difference
Where the purchase price exceeds the lender's valuation, the difference may require additional funding.
Stamp Duties
Applicable duties should be included in the total acquisition budget rather than treated as a later expense.
Legal and Professional Fees
Conveyancing, valuation and other professional costs may vary according to the transaction.
Renovation Deposit and Initial Works
Some renovation and professional fees may become payable soon after completion.
Immediate Repairs
Roofing, waterproofing, electrical, plumbing or drainage issues may require early attention.
Liquidity Buffer
A reserve may help buyers manage unexpected ownership and household expenses.
Stamp Duties Form Part of the Acquisition Cost
Buyers should account for Buyer's Stamp Duty and any Additional Buyer's Stamp Duty that may apply to their buyer profile and ownership position.
The final amount may depend on the higher of the purchase price or market value and on the buyer's circumstances. Remissions, joint purchases, trusts, entities and non-standard ownership structures may require separate assessment.
Stamp Duty Planning Considerations
Confirm the buyer profile used for the calculation
Review the number of residential properties owned
Use the relevant property value for duty purposes
Check whether any remission may apply
Allow for payment timing
Seek legal or tax advice for unusual structures
Renovation and Maintenance Should Be Included in Affordability
Landed homes may require a wider range of maintenance and upgrading work than many strata properties. The scale of work depends on the age, condition, design and intended use of the property.
Buyers who intend to renovate, carry out addition and alteration works or explore rebuilding should avoid treating the purchase price as the full project cost.
Initial Works
Roof and waterproofing review
Electrical and plumbing systems
Drainage and external works
Structural or professional assessment
Interior renovation and fittings
Ongoing Ownership
Routine maintenance
External painting and repairs
Garden and landscape upkeep
Pest-management considerations
Future replacement of ageing systems
Affordability Is More Than Meeting the Monthly Instalment
A property may appear affordable based on the estimated monthly loan repayment, but a more complete review should consider the buyer's position before, during and after the purchase.
How much cash and CPF will remain after completion?
Can the household continue saving after servicing the loan?
Is there sufficient liquidity for renovation and unexpected repairs?
Would the repayment remain manageable if income changes?
Does the purchase restrict other family or investment plans?
Can the property be held comfortably during weaker market conditions?
The most useful affordability figure is not always the highest price a buyer can purchase. It may be the price that leaves sufficient room for ownership, renovation and future financial flexibility.
Common Financing Misconceptions
"The bank's maximum loan is my true budget."
The maximum amount a lender is prepared to offer may not reflect the buyer's preferred repayment comfort, renovation needs or future commitments.
"CPF can cover every upfront expense."
CPF usage remains subject to prevailing rules and transaction requirements. Buyers should identify which costs may still require cash.
"Renovation can be planned after completion."
Even where the final design has not been decided, buyers may benefit from setting aside an initial renovation and contingency budget before committing to the purchase.
"Higher income automatically means comfortable affordability."
Household expenditure, existing debts, financial dependants, future plans and income stability may all affect repayment comfort.
Frequently Asked Questions
Can CPF be used to buy landed property?
CPF Ordinary Account savings may generally be used for eligible residential property purchases, subject to prevailing CPF rules, applicable limits and the buyer's individual circumstances. Buyers should confirm their eligibility before relying on CPF for financing.
Is the maximum loan always the best option?
Not necessarily. While a buyer may qualify for a higher loan, many also consider future cash flow, emergency savings, renovation plans and overall financial flexibility before deciding how much to borrow.
Besides the purchase price, what other costs should buyers prepare for?
Buyers commonly budget for stamp duties, legal fees, valuation-related costs, renovation works, moving expenses, maintenance and an appropriate contingency reserve depending on the condition of the property.
Should renovation costs be included when planning affordability?
Many buyers find it useful to consider renovation and repair costs together with the purchase, particularly for older landed homes where upgrading works may be more extensive.
Can this guide replace financial advice?
No. This guide is intended for general educational purposes only. Financing arrangements, CPF usage, loan approval and tax considerations depend on individual circumstances and should be confirmed with the relevant professionals.
Continue Your Landed Property Journey
Next recommended reads in Landed Property Guides.
You May Also Find These Guides Useful
Recommendations from related property categories.
Property Planning Tools
Use these calculators and financial tools to understand the numbers behind your property decision.
Continue Learning
Related Landed Property Guides
Landed Property Buying Guide Singapore
Begin with the complete overview before exploring financing considerations.
Read GuideFreehold vs Leasehold Landed Property
Understand how tenure may influence long-term ownership, financing and investment considerations.
Read GuideBuyer Cash Required Calculator
Estimate your potential cash and CPF requirements before purchasing a residential property.
Open CalculatorProperty Affordability Planner
Compare financing scenarios and estimate a comfortable property budget.
Open PlannerImportant Disclaimer
This article is provided for general educational purposes only and should not be regarded as financial, legal, tax or lending advice. Financing availability, CPF usage, stamp duties, affordability, ownership structures and regulatory requirements vary according to each buyer's circumstances and prevailing regulations. Buyers should obtain professional advice before making any property purchase decision.
Planning to Buy a Landed Property?
Every landed property purchase is different. Reviewing financing, CPF usage, cash flow and long-term affordability together often provides a clearer picture than looking at any one factor in isolation.
Speak With William